


A fixed-rate home loan has a constant interest rate throughout the loan term, so your EMI stays the same for the entire tenure — offering predictable payments and protection if market rates rise later.
Fixed or Floating Home Loan Interest Rate: Which is Better?
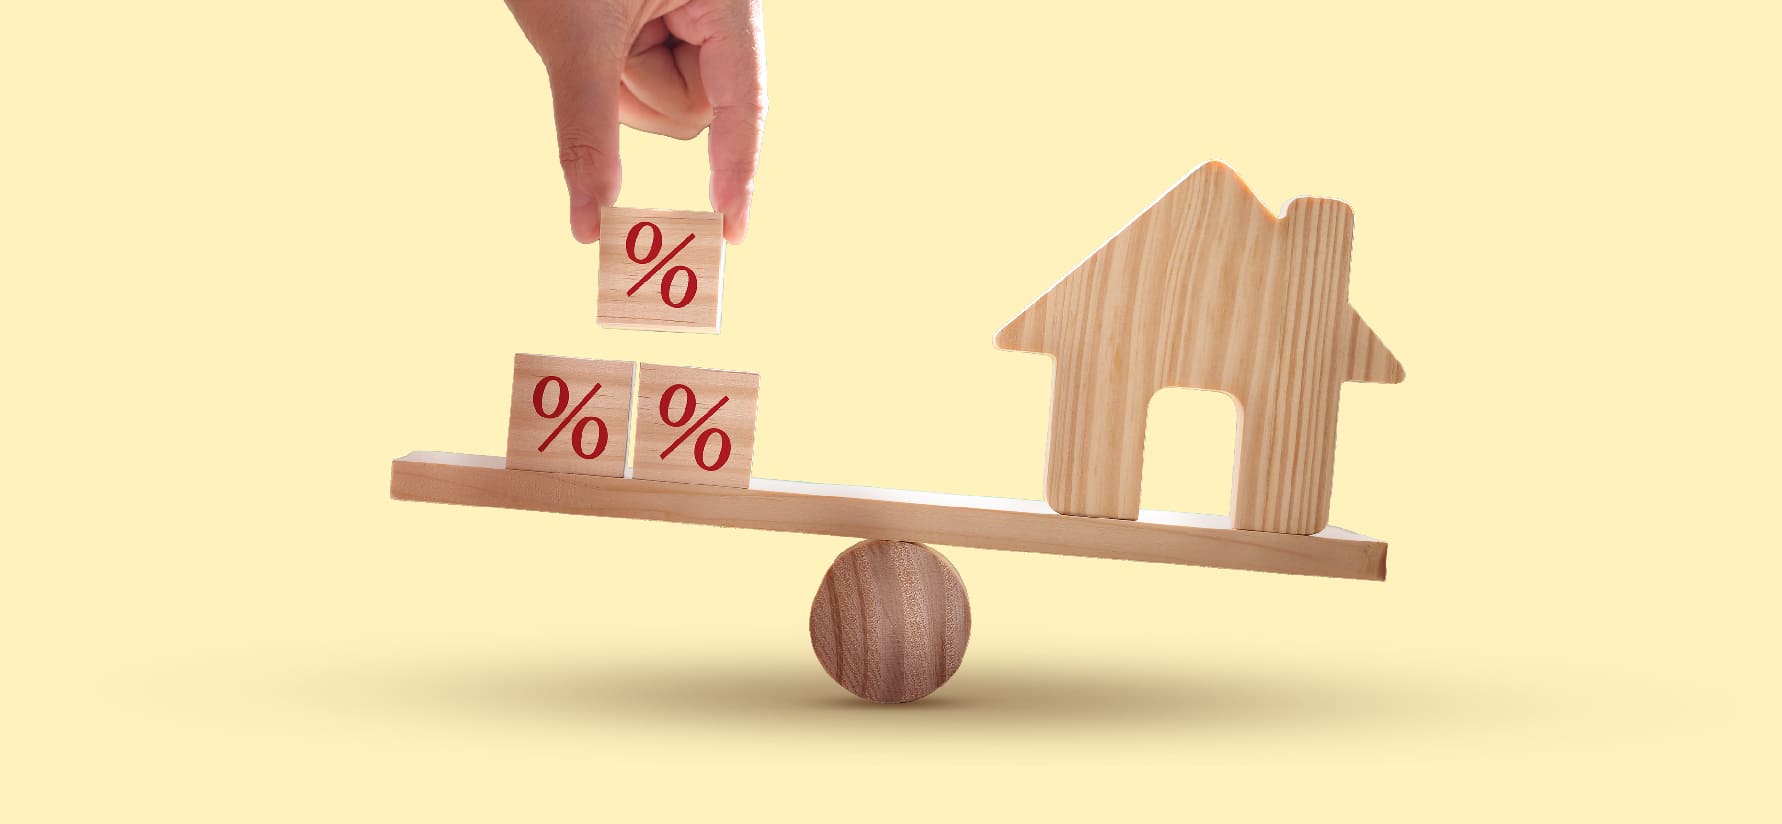
Buying a home is one of the most significant financial decisions you’ll make in your lifetime. With various home loan options available, one crucial aspect to consider is the interest rate. The type of interest rate you choose can impact your finances for years to come.
Choosing the right home loan interest rate is essential as it affects your financial stability and affordability. Home loans come in different types, primarily categorized into fixed-rate and floating-rate loans. Each type has its advantages and considerations, making it crucial to understand how they influence your finances. Understanding these options will help you make a sound decision that aligns with your financial budget and market expectations.
Decoding Fixed-Rate & Floating-Rate Home Loans
A fixed-rate home loan features a constant interest rate throughout the loan term, ensuring stable and predictable monthly payments without fluctuations due to market conditions. In contrast, a floating-rate home loan has an interest rate that varies based on market benchmarks, which means your payments can change over time. While floating-rate loans can offer lower initial rates and potential savings if market rates fall, they also carry the risk of increased costs in case the rates rise.Understanding Fixed-Rate Loans
Fixed-rate home loans are designed with a constant interest rate throughout the loan tenure. This means your monthly EMI (Equated Monthly Installment) remains intact for the entire loan term, providing a stable and predictable repayment schedule. Here are a few benefits of fixed-rate loans;- Predictable Payments
- Financial Planning
- Protection Against Rising Rates
When to Opt for Fixed-Rate Loans?
- Comfortable with EMI and Steady Payments
- Expect Interest Rates to Rise
- Interest Rate Impact
What is Floating-Rate Home Loans?
Floating-rate home loans, also known as variable-rate loans, have an interest rate that fluctuates based on market conditions. The rate is usually linked to a benchmark interest rate, which can change periodically.Why Choose Floating-Rate Loans?
- Interest Rate Variation
- Potential for Lower Interest Rates
- No Prepayment Penalty
- Suitable for Long-Term Loans
- Market-Dependent
- Frequent Rate Reviews
- Flexibility in Loan Tenure
When to Opt for Floating-Rate Loans?
- Interest Rates to Fall
- Market Trends
- Short-Term Savings
Fixed vs. Floating Rate Home Loan Comparison
Both fixed and floating rate home loans carry their own set benefits and risks. However, there is a certain difference between fixed and floating interest rates that must be assessed before opting for the loan.- Fixed Rate
- Floating Rate
What to Consider While Choosing Fixed Vs. Floating Rate Loans?
- Financial Stability
- Market Trends
- Risk Tolerance
Pros and Cons: Fixed-Rate & Floating-Rate Home Loans
- Fixed Rate Pros:
- Fixed Rate Cons:
- Floating Rate Pros:
- Floating Rate Cons:
Switching Between Fixed and Floating Rates
Some lenders offer the flexibility to switch between fixed and floating rates during the loan tenure. This can be beneficial if your financial situation or market conditions change.Key Considerations to Check Before Switching
- Assess Timing and Costs
- Market Conditions and Financial Situation
Conclusion
Fixed-rate loans provide stability and predictability, making them perfect for individuals who prefer steady payments and seek protection from rising interest rates. Floating-rate loans provide flexibility and potential savings, which is ideal for those who expect interest rates to decrease or align with market trends. It is essential to check the current home loan interest rates, market trends, and personal preferences before choosing between fixed and floating rates. Besides this, you should also compare home loan interest rates to make a sound decision that fits your financial goals. For more such industry insights, stay tuned to BeyondWalls – an online property portal.FAQ
2. What is a floating-rate home loan?
A floating-rate (or variable-rate) home loan has an interest rate that fluctuates based on a market benchmark, reviewed periodically (typically quarterly or annually). Your EMI can go up or down as rates change.
3. Which is cheaper initially — fixed or floating rate?
Floating-rate loans typically start with lower initial interest rates than fixed-rate loans, though fixed rates offer more certainty over the full loan term.
4. When should I choose a fixed-rate home loan?
Fixed rates suit borrowers who want steady, predictable EMIs, expect interest rates to rise in the future, or are risk-averse about how rate changes could affect their finances.
5. When should I choose a floating-rate home loan?
Floating rates suit borrowers who expect interest rates to fall or stay stable, are comfortable with some payment variability, and want the potential for short-term savings.
6. Do floating-rate loans have prepayment penalties?
Many floating-rate loans allow prepayment without penalties, giving borrowers flexibility to pay off the loan early or make additional payments without extra cost.
7. Can I switch between fixed and floating interest rates during my loan tenure?
Some lenders allow switching between fixed and floating rates during the loan term. Before switching, it’s important to evaluate the timing, any associated fees, and whether current market conditions support the change.
8. What factors should I consider before choosing between fixed and floating rates?
Consider your financial stability and income predictability, current market trends and rate forecasts, and your personal risk tolerance for potential payment fluctuations.
Thank you. Your comment will be visible after an approval.
Comments (0)
No comments found.Featured Articles
Proven Framework for High Velocity Launches
Recent Articles
Pune Homebuyer’s 2026 Shortlist: How to Choose Between Wakad, Baner, Hinjawadi and Tathawade
From Property Search to Shortlisting: How a Real Estate Platform Can Simplify Buying a Home in India
Mumbai 3.0: How Infrastructure Is Redrawing Mumbai’s Real Estate Map
The Smarter Way to Find Your Next Home: Using a Real Estate Platform to Compare Projects, Locations and Prices
What Is IFMS in Real Estate? Meaning, Benefits, Charges & What Homebuyers Should Know
Add your comment